
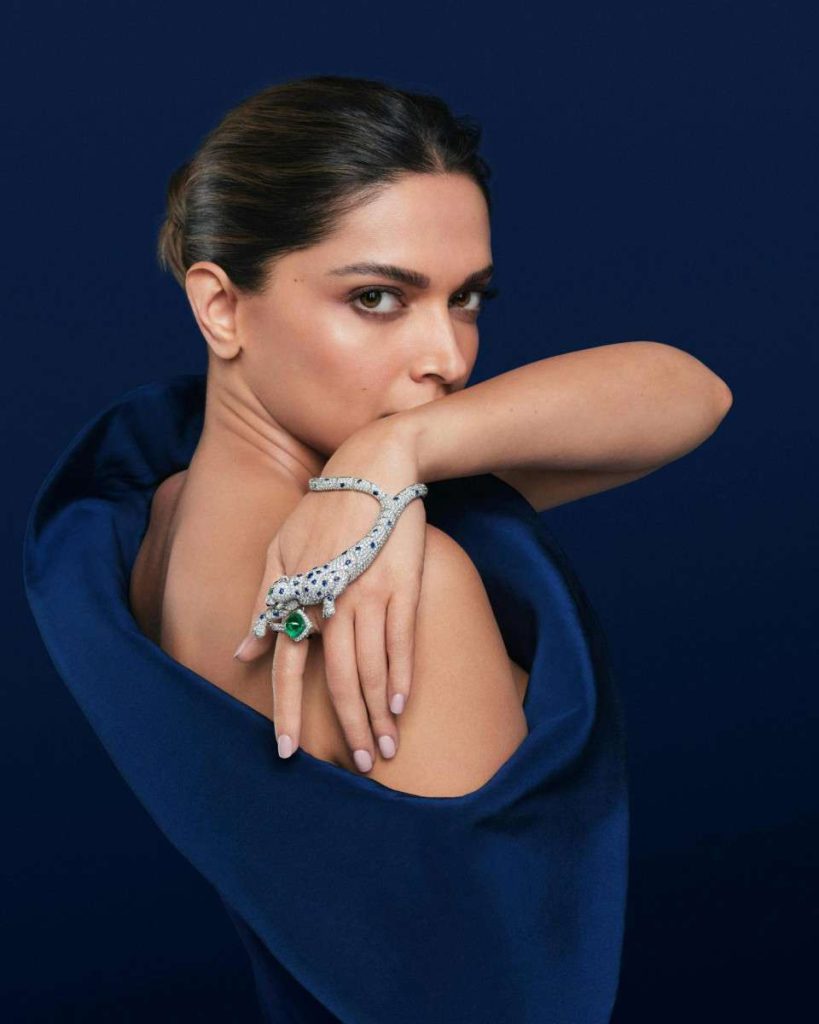
Group sales rose 20% at constant exchange rates to €6.3 billion for the quarter ended June 30, beating the 11% analysts had forecast. Jewellery led the way, up 24%, driven by the Group’s four jewellery maisons – Buccellati, Cartier, Van Cleef & Arpels and Vhernier – delivering a seventh consecutive quarter of double-digit growth. Shares hit a record in Zurich, up as much as 7.4%, and the broader luxury sector rallied with it.
The headline is straightforward. The more interesting question is why jewellery continues to behave so differently from the rest of luxury.
The category story: Jewellery is separating from luxury

This wasn’t a case of luxury enjoying a broad rebound and Richemont simply riding the wave. If anything, the opposite is true. Much of the sector is still grappling with softer aspirational demand, a slower Chinese consumer and growing fatigue after years of price increases across handbags and ready-to-wear. Richemont’s Jewellery Maisons continue to move against that backdrop.
Kepler Cheuvreux analyst Jon Cox told Reuters that Richemont remains the market leader in branded jewellery and dress watches, where demand is currently stronger than in other luxury categories. He also argued that buyers are increasingly drawn to products with intrinsic value and that wealth created by the AI investment boom is finding its way into high-end jewellery purchases.
Jefferies, the independent investment bank, described Richemont’s results as “blow-out” and said jewellery is likely to remain a disproportionate winner as luxury earnings season unfolds, with Richemont continuing to gain share within the category. That distinction matters. Two trends appear to be happening simultaneously.
- Jewellery is proving more resilient than leather goods or apparel
- Richemont appears to be capturing a disproportionate share of that resilience.
Richemont’s business is unusually weighted toward jewellery. Most other big luxury groups aren’t built that way. LVMH and Kering, for instance, get much more of their revenue from leather goods, ready-to-wear, and fashion than from jewellery. So when Richemont posts a whopping 24% jewellery-driven growth, that tells you jewellery demand specifically is strong. It doesn’t tell you luxury demand broadly is strong.
The story, then, isn’t that luxury has recovered. It’s that jewellery has become the strongest-performing segment within luxury, and Richemont is setting the pace.
It’s less a China story than a pricing story
The obvious explanation for a result like this would be a macro tailwind—a currency move, stronger tourism or a broader wealth effect. None fully explains what happened. Growth was broad-based across regions, with the Middle East the only notable exception. Even there, Richemont said local demand largely offset weaker tourist spending.
What repeatedly surfaced in analyst commentary instead was pricing. Bernstein’s Luca Solca noted that Richemont successfully serves both ends of the market. A high jewellery piece can sell for $1 million +, while a Cartier ring or bracelet remains accessible at roughly $2,000 to $5,000. Both segments grew during the quarter, and growth was broad-based rather than concentrated in exceptional high jewellery sales. That kind of consistency doesn’t happen by accident. It’s what pricing architecture built for the long term looks like.
Heritage and innovation reinforcing one another

One detail stood out. Cartier’s long-established Love and Panthère collections continued to perform strongly alongside newer launches such as Clash de Cartier Colors. That’s an important strategic signal. Heritage collections aren’t competing with innovation—they’re creating the stability that allows new collections to build over time.
Read more: The Franchise Effect: Why One Jewellery Idea Wins
Retail did the heavy lifting
Owned retail sales rose 24% to €4.5 billion, representing roughly 71% of group revenue. Wholesale and royalty income increased 9%, while online retail grew 18%. Growth was strongest where Richemont controls the customer relationship end to end. Years of investing in directly operated boutiques are now translating into measurable operating leverage.
An insider’s perspective
I spent several years as CMO at Alfred Dunhill, one of Richemont’s Maisons, so I’ve seen this operating model from the inside. What stands out to me isn’t just the 24% growth rate. It’s the consistency. Seven consecutive quarters of double-digit jewelry growth point to something structural rather than cyclical. Inside a Maison, that’s the difference between building long-term brand equity and reacting quarter to quarter.
What’s really happening is a price ladder, not two isolated customer groups. Cartier maintains the same design language, craftsmanship and brand story at every rung, whether someone buys a $4,000 bracelet, a $40,000 necklace or a multimillion-dollar high jewelry commission. Many brands struggle to stretch across that spectrum without diluting one end or the other. Richemont has largely avoided that trap because the brand narrative doesn’t change as you move up or down the ladder.
The retail mix matters for another reason, and it’s a distinction I learned the hard way in a Richemont boardroom. I once used the phrase “owning the customer” and got pulled up on it immediately. It was made abundantly clear that language like that was considered disrespectful to the client relationship, practically a CEM (career-ending move) to say out loud. The correct term, and the one that actually reflects how these Maisons are trained to think, is “owning the customer experience”.
It’s not about higher margins, and it’s certainly not about possession. It’s about controlling the moment a purchase decision gets made, the story that surrounds it, and the relationship that continues after. That’s difficult to replicate through wholesale distribution, and this quarter illustrates the cumulative value of getting it right.
Why jewellery is winning
Pull the threads together and the picture is clear. Jewellery isn’t riding a luxury rebound. It’s outperforming a sector that is largely still struggling, and Richemont is the clearest evidence of why.
The architecture holds because the story never changes as you move up the ladder, as already noted. What’s harder to copy is the rest of it. Heritage collections fund the credibility that new launches need to land. Growth is concentrated in owned retail, where Richemont controls the relationship rather than renting it out to a wholesale partner. And the demand itself is being driven by wealth generated by the AI investment boom, landing in a category built to receive it, rather than one still working through years of price increases it can’t fully explain.
None of that is luck, and none of it is easily copied. It’s the result of years of deliberate choices about pricing, product and distribution, made well before this quarter. Richemont’s results, taken on their own, point to something bigger than one strong quarter. They point to jewellery as the standout performer in luxury right now, built on fundamentals & strategic rigor that the rest of the sector hasn’t matched.
Like this? Read Paris Couture Week 2026: Why rarity became luxury’s greatest asset